12 Personal Finance Tips That Actually Build Wealth in 2026
Smart money management rarely comes from one big decision. It grows from dozens of small, repeatable habits that compound over time. The best personal finance tips are simple enough to start this week yet powerful enough to change your net worth over a decade. This guide gathers the strategies that consistently work in 2026, whether you are paying down debt, building your first emergency fund, or finally learning to invest.
You do not need a finance degree to get ahead. You need a plan, a little discipline, and a handful of tools that keep you honest. Let’s walk through the habits that matter most and how to put them to work.
Why Personal Finance Tips Matter More Than Ever
Inflation, rising rents, and higher borrowing costs have squeezed household budgets across the US and beyond. According to the Federal Reserve’s 2024 report on the economic well-being of US households, a large share of adults still could not cover an unexpected $400 expense with cash. That single statistic explains why foundational money habits are not optional anymore.
The good news is that control is closer than it feels. When you track spending, automate saving, and trim a few recurring costs, progress arrives faster than most people expect.
Start With a Clear Money Baseline
Before you optimize anything, measure it. Add up your monthly income, list every recurring bill, and note your total debt. This snapshot is your starting line. You cannot improve a number you have never written down.
Budgeting Habits That Stick
Most budgets fail because they are too strict. A workable budget leaves room for real life while still protecting your goals.
- Use the 50/30/20 rule. Send 50% of take-home pay to needs, 30% to wants, and 20% to savings and debt payoff.
- Pay yourself first. Move money to savings the day you get paid, not whatever is left at month’s end.
- Give every dollar a job. Assign income to categories so nothing drifts away unnoticed.
- Review weekly. A five-minute Sunday check keeps small leaks from becoming floods.
Think of your budget the way you would think of hiring an experienced local team for a job you would rather not do yourself: the right system does the heavy lifting so you can focus on results instead of daily stress.
Automate the Boring Parts
Automation removes willpower from the equation. Schedule automatic transfers to savings, set bills on autopay to dodge late fees, and let a round-up feature invest your spare change. The less you touch the process, the more reliable it becomes.
Best Money Apps to Simplify Your Finances
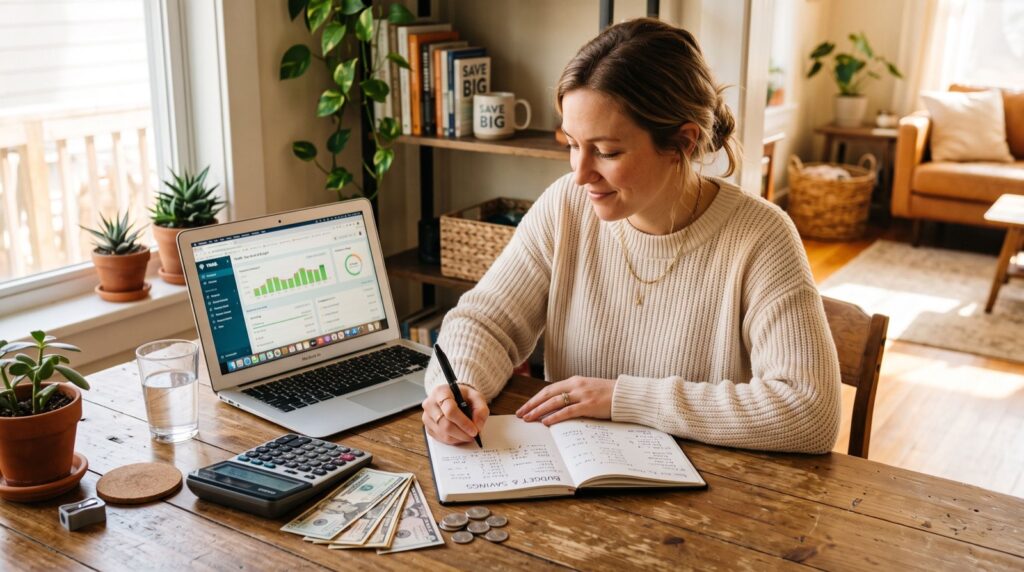
Technology has made money management genuinely easier. Modern money apps can categorize transactions, flag unusual charges, and nudge you toward your goals automatically. The right stack of tools turns a chore into a background process.
Here is how the main categories compare so you can choose what fits your situation.
| App Category | Best For | Typical Cost | Key Benefit |
|---|---|---|---|
| Budgeting trackers | Seeing where money goes | Free to $15/mo | Automatic categorization |
| Peer-to-peer payment | Splitting bills, fast transfers | Free (fees on instant) | Instant money movement |
| Micro-investing | New investors | $1–$5/mo | Round-up investing |
| High-yield savings | Emergency funds | Free | Higher interest rates |
Pick one app per category at most. Juggling too many tools creates friction, and friction is where good habits go to die.
Smart Ways to Attack Debt
Debt quietly drains the money you could be saving or investing. Two proven payoff methods help you regain momentum.
- The avalanche method: Pay minimums on everything, then throw extra cash at the highest-interest balance first. This saves the most money over time.
- The snowball method: Pay off the smallest balance first for a quick psychological win, then roll that payment into the next debt.
Choose the avalanche if you are motivated by math and the snowball if you are motivated by momentum. Both work, so pick the one you will actually follow.
Watch Your Interest Rates
High-interest credit card debt can erase years of investment gains. If you carry a balance, call your issuer and ask for a lower rate, or explore a balance-transfer offer. One phone call can save hundreds of dollars.
Build an Emergency Fund First
An emergency fund is the foundation beneath every other goal. Aim for one month of expenses to start, then build toward three to six months. Keep this cash in a high-yield savings account where it stays liquid but still earns interest.
This buffer stops a flat tire or medical bill from becoming new credit card debt. It is the single most stabilizing of all personal finance tips because it protects every other plan you make.
Grow Your Money for the Long Term
Once your debt is under control and your emergency fund is funded, let compound growth work for you. Time in the market beats timing the market almost every time.
- Contribute enough to any employer retirement match—it is free money.
- Favor low-cost, diversified index funds over chasing individual hot stocks.
- Increase contributions by 1% each time you get a raise.
- Reinvest dividends automatically to accelerate compounding.
Remember that this is general education, not individual investment advice. For decisions about specific products, consult a licensed professional who knows your full situation.
How Much Should You Save Each Month?
A practical target is 20% of take-home pay split across emergency savings, retirement, and goals. If that feels impossible today, start at 5% and raise it quarterly. Consistency matters far more than the starting amount.
Frequently Asked Questions
What is the best first step to improve my finances?
Track every dollar for 30 days. Awareness alone usually reveals easy cuts, and it gives you the accurate baseline you need before building a budget or choosing money apps.
How much emergency savings do I really need?
Start with one month of core expenses, then work toward three to six months. Households with variable income or a single earner should lean toward the higher end for extra security.
Are budgeting apps safe to use?
Reputable apps use bank-level encryption and read-only connections. Enable two-factor authentication, use a strong unique password, and stick to well-reviewed providers to keep your data protected.
Should I pay off debt or invest first?
Clear high-interest debt before investing beyond any employer match, since credit card interest usually outpaces market returns. Once high-interest debt is gone, invest and save at the same time.
Your Next Move
The most valuable personal finance tips share one trait: they reward people who start now and stay consistent. Choose two habits from this guide this week—perhaps automating your savings and downloading one budgeting app—and build from there. Small steps, repeated faithfully, create the kind of financial stability that feels impossible until suddenly it is routine. Ready to take control of your money today? Explore more practical guides and tools at WalletWisp and turn these tips into lasting results.